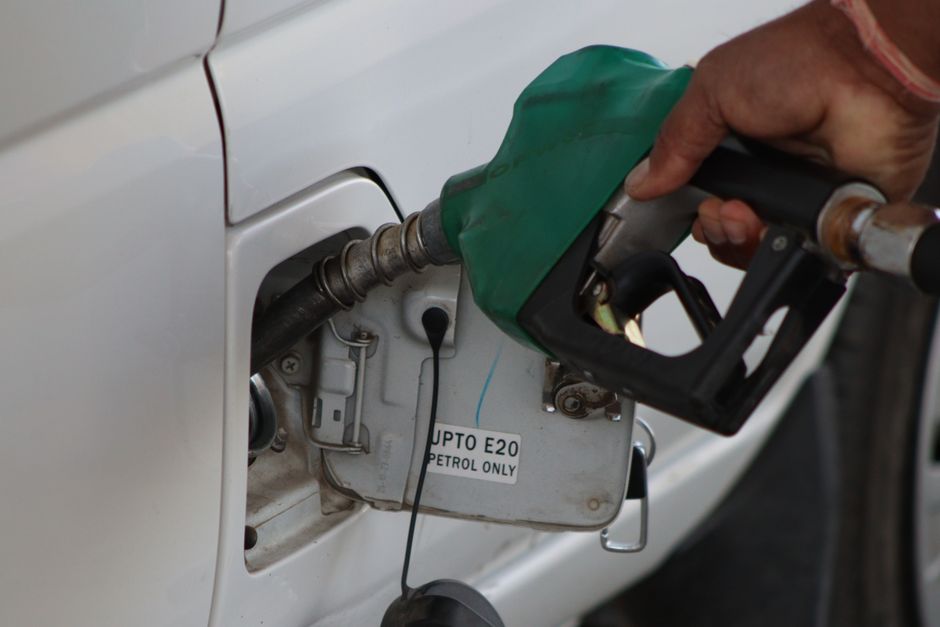
Spot LNG hits $26/mmBtu across Asia—but India keeps buying
As soaring prices push other Asian buyers to coal and nuclear, India remains the marginal buyer of expensive LNG, driven by extreme heat, renewable-storage mismatch, and no other grid options.
Asian liquefied natural gas spot prices reached $26 per million British thermal units in mid-September—their highest level since December 2022—as supply disruptions in the Middle East squeeze global markets. The shock stems from Iranian missile strikes on Qatar's Ras Laffan facility in March, which disabled 12.8 million tonnes per annum of export capacity, combined with the closure of the Strait of Hormuz, through which nearly all Qatari LNG must transit. QatarEnergy has extended force majeure declarations into October and beyond, wiping out roughly a quarter of Asian LNG flows.
At these prices, demand destruction is textbook. China, the world's largest importer, has slashed spot purchases—September arrivals forecast at 4.32 million tonnes, down from 5.32 million a year prior. Japan and South Korea have pivoted toward coal, nuclear baseload, and conservation. Pakistan rejected LNG offers above $27 per mmBtu as unaffordable. State-controlled GAIL may have secured October and November cargoes at roughly $25.10–25/mmBtu around September 1—among the highest prices India has faced since 2022.
Yet India continues to buy. The driver is not commercial optimism but grid desperation. India has installed 154.2 GW of solar capacity by April 2026—pushing daytime electricity prices toward zero when the sun is abundant. But battery and storage capacity have not kept pace. At night, cooling demand remains elevated and cities are hot, creating repeated nighttime shortfalls. On May 21, India faced a 2.5 GW nighttime shortfall despite record solar generation. Gas-fired peaking plants are the only dispatchable resource available to fill those gaps at short notice.
As a result, LNG has shifted from fuel to grid necessity. Where Northeast Asian buyers can swap expensive LNG for coal or nuclear, India cannot: those alternatives are either unavailable or economically constrained by utility cost-recovery rules. India faces potential supply curtailments of up to 1.5 million tonnes per month due to Qatari disruptions, diverting available gas to power, fertilizers, and city gas distribution. The U.S. became India's largest LNG supplier by May 2026, with volumes surging from 137,000 to 907,000 tonnes monthly, alongside expanded purchases from Nigeria and Oman.
This dynamic carries geopolitical weight. India's vulnerability to expensive marginal LNG is partly a function of its rapid solar buildout without commensurate storage—a policy bet on renewable capacity that now leaves New Delhi exposed to Middle East supply shocks. It is also a reminder that while global LNG demand has destroyed in Northeast Asia, South Asian grid constraints are forcing price-inelastic buying that sustains market pricing at levels most buyers cannot bear.
How could this affect you
Traced by who's actually in the path of this — not everyone is.
Likely
Indian utilities and power companies
Sustained high spot LNG prices ($25–26/mmBtu) combined with forced grid reliance on gas during heat waves and nighttime shortfalls could push operating costs above cost-recovery thresholds, straining margins. If utilities cannot pass costs to consumers, financial stress on major Indian power operators (including coal-fired plants forced to run less) could accelerate.
Likely
LNG exporters and traders
India's inelastic demand at high prices sustains the $25–26/mmBtu floor for Asian spot cargoes. If India is forced to reduce procurement due to financial or policy constraints, the market would need to absorb the loss, likely collapsing prices across all Asian buyers.
Likely
Indian fertilizer and petrochemical producers
Gas allocation has been diverted to power and essential sectors; urea output and other energy-intensive industries are being squeezed by Qatari disruptions and curtailed LNG supplies. Prolonged supply rationing could reduce output and exports, affecting downstream industries and food security.
Possible
Global renewable energy investors
India's solar boom without matching storage infrastructure has created a real-time gap that expensive fossil fuels are forced to fill. If extended grid reliance on high-cost gas demonstrates the limits of storage-free solar scaling, it could influence investor confidence and policy in countries pursuing similar strategies.
Sources
Every claim here traces back to reporting you can read yourself.